Insider Mortgage Logo

Self-Employed Borrowers

Mortgage Qualification & Alternative Income Documentation Strategies

Being self-employed can offer tremendous financial opportunities, but when it comes to getting a mortgage, it can also create some unexpected challenges. For business owners, entrepreneurs, freelancers, and independent contractors, income often works differently. Even highly successful borrowers with excellent credit, substantial assets, and strong cash flow can find themselves struggling to qualify for a traditional mortgage.

START WITH YOUR TAX RETURNS

Our first step is always to comprehensively review your financial situation. We will see if we can use standard “full-documentation” underwriting using one or two years of your tax returns so we can get you the best priced rates out there. However, if your self-employed situation has one or more of these income qualifying challenges, we have solutions.

COMMON CHALLENGES

1. Tax Write-Offs Reduce Qualifying Income

One of the greatest ironies of self-employment is that strategies used to minimize taxes can also reduce mortgage borrowing power. Business owners routinely deduct legitimate expenses such as vehicles, travel, equipment, office costs, and other business expenditures. While these deductions can substantially reduce their tax liability, they may also reduce the income traditional mortgage lenders recognize when determining how much a borrower can qualify for.

2. Variable Income

Unlike salaried employees who receive a predictable paycheck, self-employed borrowers often experience significant fluctuations in income from month to month or year to year. A real estate professional, for example, might earn most of their annual income from a handful of large transactions, while a business owner may experience seasonal revenue cycles.

3. Declining Income

Even a temporary decline in income can create challenges when applying for a mortgage. Conventional lenders typically evaluate income trends over the previous two years, and when earnings decline, they may use the most recent year's lower income rather than a two-year average.

4. Limited Self-Employment History

Traditional mortgage lenders generally prefer to see at least two years of established self-employment income. This can create significant challenges for newer business owners and professionals transitioning from salaried employment—even when their earnings are increasing substantially.

5. Complex Business & Income Structures

Successful entrepreneurs often earn income through multiple businesses, partnerships, LLCs, or S-corporations. Their compensation may include W-2 wages, partnership distributions, Schedule K-1 income, and profits retained within their companies.

6. Business Debt & Access to Business Funds

Business owners frequently rely on credit lines, equipment financing, business credit cards, and other forms of borrowing to operate and grow their companies. Although these obligations may be paid entirely by the business, certain debts can still affect the owner's personal debt-to-income ratio, particularly when the borrower is personally liable or the business payment history isn't adequately documented.

The Good News: There Are More Ways to Qualify

Not fitting conventional mortgage guidelines doesn't necessarily mean you can't qualify for a mortgage.

At Insider Mortgage, we understand that the financial lives of business owners and self-employed professionals rarely fit into a simple box. Beyond traditional financing, specialized mortgage programs may allow qualified borrowers to document income through business or personal bank statements, 1099 earnings, profit-and-loss statements, or other acceptable methods.

The key is understanding how your income is earned, how your business operates, and which mortgage programs are best suited to your financial circumstances.

You don't necessarily need to change the way you earn a living to qualify for a mortgage. You may simply need a different lending strategy.

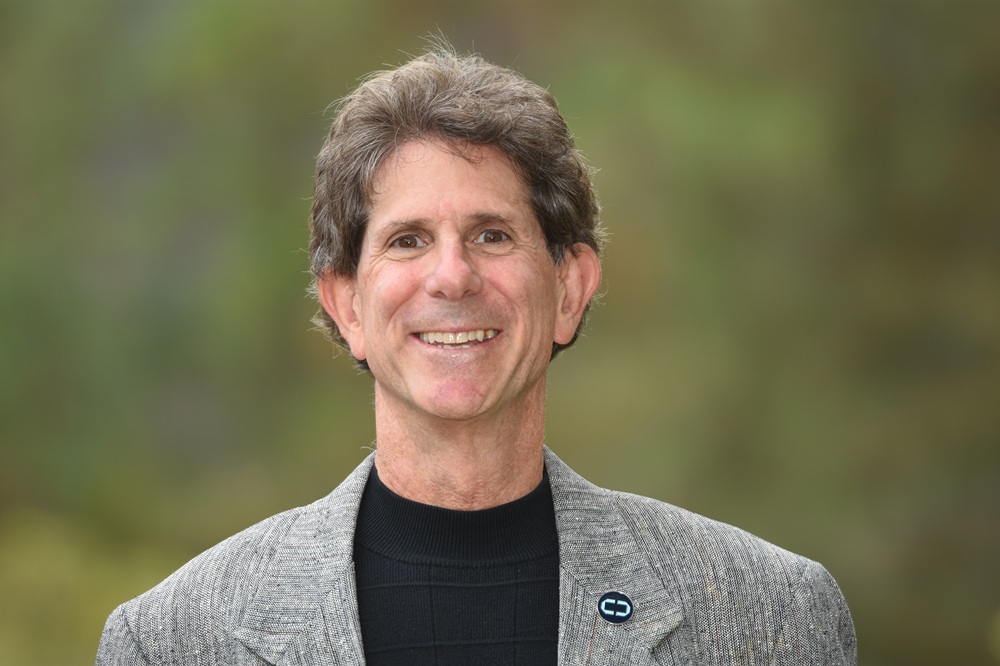
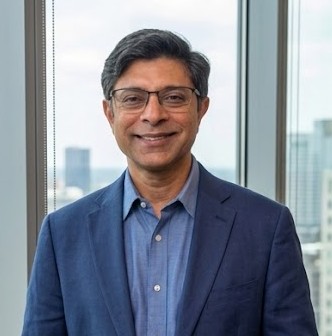
David SiderRakesh JainSchedule a call with David and Rakesh to explore your options

INSIDER SOLUTIONS

1. Bank Statement Loans

Instead of relying on tax returns, these programs typically evaluate 12 or 24 months of personal or business bank statements. Lenders analyze eligible monthly deposits to calculate the businesses monthly gross revenue. Then, depending on the type of business, the lender applies an appropriate business expense factor to determine qualifying net income. This can be an excellent option for business owners with strong cash flow but significant tax deductions.

2. 1099 Income Loans

Designed for independent contractors, consultants, and commission-based professionals, these programs typically use one or two years of 1099 forms rather than tax returns. Lenders calculate qualifying income by applying an allowable expense factor to reported earnings. This approach may recognize substantially more income than traditional tax-return underwriting.

3. Profit & Loss (P&L) Loans

Certain lenders allow self-employed borrowers to qualify using a business profit-and-loss statement over the most recent 12 months versus relying on the previous year’s tax return. The P&L is often prepared or verified by a qualified tax professional. This solution is also useful for the business owner who receives periodic but not standard income. The revenues will appear on a financial statement without underwriters having to scrutinize the deposits that would be reflected on bank statements.

4. Asset Utilization Loans

For borrowers with substantial savings, investments, or retirement assets, some programs allow qualifying income to be calculated from eligible assets rather than employment earnings. Lenders use a formula to convert those assets into an equivalent monthly income. This can be particularly useful for supplementing business income.

Success Stories

★★★★★

"I'm self-employed, so getting financing for a new construction condo in Redondo Beach came with its own set of hurdles. Rakesh handled it using alternative documentation and got it done. But what really stood out was how he managed the whole process. He was the quarterback. He kept tabs on everyone involved, the escrow, the title, the insurance people, making sure nothing fell through the cracks and that everything stayed on track to close on time. A diligent mortgage broker to know, with great follow through and the kind of person who actually coordinates well between all the moving parts. I felt at ease with him in my corner. A 5 star service for homebuyers!"

DM
Drew Manier
Google Review
★★★★★

"I was introduced to David at Insider Mortgage by my real estate agent as a first-time homebuyer, and I chose to work with him because of how clearly he explains everything. He breaks down every scenario and option so you can truly understand the mortgage process. Unlike other lenders who send a short email about rates and credits, David records detailed videos covering refinancing scenarios and loan programs, including bank statement loans for 1099 business owners. He gives honest guidance, even advising friends to wait on a purchase when market conditions suggested prices would drop. That level of transparency made me confident in working with him and recommending him to others. David’s professionalism and straightforward approach make him stand out as a top mortgage professional in Southern California. He takes the time to educate clients so even first-time buyers can understand complex financial details. By the end of the process, I felt informed and empowered, and my friend also gained valuable insight through his guidance. We purchased a home with a pool and partial ocean view, and I would absolutely call David again or recommend Insider Mortgage to anyone looking for a trusted mortgage lender."

SA
Sam Alnweiran
Google Review
David Sider
David SiderManaging Partner
Rakesh Jain
Rakesh JainSenior Loan Officer & Partner

Talk Directly with David & Rakesh About Your Self-Employed Scenario

You will never be handed off to a junior loan officer or call center. Schedule a one-on-one call with David Sider and Rakesh Jain to walk through your tax returns, bank statements, 1099s, or business structure and see which mortgage strategy gives you the strongest buying power.

Prefer to call or text us right now? Reach us directly at (858) 848-5653

Request a Consultation with David and Rakesh

When is a good time to connect?

Let us know what works best for you.

Preferred day
Preferred time (Pacific Time)